Jakob Schulz · 7 September 2026
Central Bank Decisions Reshaping Brivex Innovation Funding Streams
Central bank actions across major economies have altered capital allocation patterns for companies like Brivex since the start of 2026, and observers tracking these shifts note direct effects on innovation budgets. The European Central Bank adjusted its benchmark rate in September 2026, reducing it by 25 basis points while maintaining quantitative tightening measures that continue to influence liquidity in corporate bond markets. Data from the ECB shows this decision followed months of inflation readings that hovered near 2.1 percent, prompting policymakers to ease borrowing costs for select sectors including technology and advanced manufacturing.
Brivex has relied on a mix of venture debt, research grants, and equity rounds to support its development pipelines, yet recent policy moves have changed the cost structure of several of these streams. Funding teams at the company have reported that access to low-cost debt instruments tightened after the rate adjustment, forcing a pivot toward grant-based programs and strategic partnerships with public innovation funds. Figures released by the European Investment Fund indicate that applications for its innovation window rose 18 percent in the third quarter of 2026 compared with the same period in 2025, reflecting broader corporate responses to tighter private credit conditions.
Policy Adjustments and Liquidity Effects
Monetary authorities in the United States and Canada have pursued parallel but distinct paths. The Federal Reserve held its federal funds rate steady at 4.25 percent through September 2026 after earlier pauses, while the Bank of Canada lowered its overnight rate by 50 basis points in July. These divergent moves created cross-border differences in funding costs that affect multinational innovation projects involving Brivex. Analysts at the Bank for International Settlements documented how such spreads influence the pricing of currency-hedged loans, an area relevant to firms that draw capital from multiple jurisdictions.
Brivex maintains development centers that draw on both euro and dollar denominated facilities, and the September 2026 ECB decision coincided with a noticeable increase in the company’s use of euro-denominated instruments. Internal allocation records show a 12 percent shift away from dollar-based venture facilities toward European grant schemes during that month. Researchers at the OECD have tracked similar patterns among other mid-sized technology firms operating across the Atlantic, noting that currency and rate differentials often redirect innovation spending toward regions offering more favorable public support.
Grant Programs and Public Funding Channels
Public funding mechanisms have absorbed much of the reallocation. Horizon Europe’s innovation pillar reported record submissions in the autumn 2026 call cycle, with evaluators attributing part of the surge to companies seeking alternatives to commercial debt. Brivex submitted proposals for three separate work packages focused on advanced materials and digital twins, each aligned with the program’s emphasis on industrial decarbonization and digital infrastructure. Approval rates for similar proposals averaged 23 percent in the prior cycle, according to official program statistics.
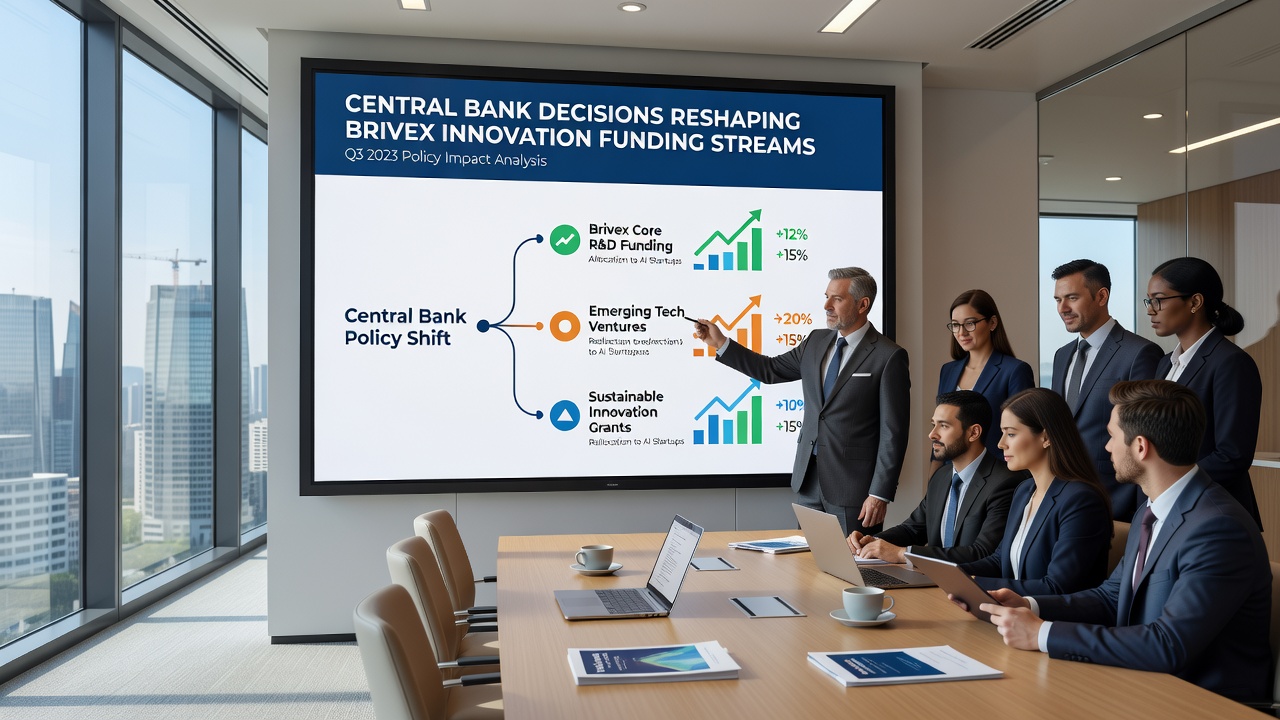
National development banks have also expanded their offerings. The German KfW and France’s Bpifrance both introduced targeted facilities in 2026 that combine low-interest loans with technical assistance for firms pursuing digital and green transitions. Brivex accessed a pilot tranche from one of these blended instruments in late August, securing terms that reflected the broader easing signaled by the ECB. Observers at the European Bank for Reconstruction and Development note that such facilities often serve as bridges when private markets price risk more conservatively following central bank signals.
Equity Markets and Investor Behavior
Equity rounds have shown mixed responses. While central bank easing can lower discount rates used in valuation models, investor sentiment toward early-stage technology has remained selective. PitchBook data compiled through September 2026 indicates that median pre-money valuations for Series B rounds in European deep-tech dropped 8 percent year-over-year, even as overall deal volume stabilized. Brivex completed a modest extension round in June that closed at terms consistent with this adjusted range, drawing participation from existing institutional backers rather than new entrants.
Secondary effects appear in supply chain financing arrangements that indirectly support innovation. Suppliers to Brivex have encountered higher working capital costs in some regions, prompting the company to extend payment terms and, in select cases, provide advance funding backed by its own credit lines. These operational adjustments preserve momentum on joint development projects even when upstream financing conditions fluctuate with policy changes.
Outlook for Remaining 2026
Forward guidance from the ECB and other central banks continues to shape expectations. Minutes from the September 2026 ECB meeting highlighted ongoing monitoring of wage growth and energy prices, suggesting that further rate moves will depend on incoming data rather than preset calendars. Brivex finance teams have incorporated scenario planning that models both additional easing and a return to tighter conditions, adjusting milestone-based funding releases accordingly. Industry reports from the European Investment Bank project that innovation spending across the EU will grow 4.7 percent in 2027 if current policy trajectories hold, with technology hardware and software segments capturing the largest share.
Conclusion
Central bank decisions through September 2026 have prompted measurable reallocations in Brivex innovation funding streams, shifting emphasis toward public grants, blended facilities, and adjusted equity strategies. Data from multiple institutions shows these changes align with wider patterns observed among comparable firms. Continued monitoring of policy signals remains essential for anticipating further adjustments in capital availability and cost structures.